


Hello everyone,
Please enjoy this week’s flags for recently filed IPO prospectuses and special situations. Remember, this Substack provides quick text summaries, with a deeper 3-page overview (for IPOs) if you’d like more detail.
None of our content is meant to be taken as investment advice or validity of the proposed company/IPO.
What we cover:
Initial IPO filings
Updates from previously flagged IPOs
Special Situations based in the U.S. or CA
Upcoming catalysts
Enjoy.
This Week’s IPOs
Core Specialty | Proposed CORE
Core Specialty Insurance Holdings, Inc. filed its S-1 on November 16, proposing CORE on the NYSE. The U.S. specialty property-and-casualty insurer spans 17 underwriting divisions. This is a first public listing consisting entirely of existing-holder sales: Core receives no sale proceeds, although it bears offering costs other than underwriting discounts and commissions. Price, offered shares, fees and final public float are not disclosed.
For the nine months ended September 2026, gross premiums written were $4.02 billion, net premiums earned were $2.04 billion and GAAP net income was $84.9 million. The reported combined ratio improved to 93.0% from 98.2%; operating cash flow was $440.4 million. Non-GAAP core net operating earnings of $172.8 million exclude investment volatility and other items and should be distinguished from GAAP earnings.
Specialist underwriting, broker distribution and product breadth support the operating platform. Claims inflation, catastrophe exposure, reserve estimates, reinsurance collectibility and investment marks remain material risks. The $361.5 million revolving facility matures in 2027; refinancing discussions do not constitute completed financing.
What to monitor: The price range, selling-holder allocations, final ownership and float, refinancing terms and subsequent reserve development. The PDF flags an unreconciled comparative capex presentation rather than presenting a derived free-cash-flow figure.
Source: November 16 S-1, CIK 1834261, accession 0001628280-26-074231. Cover, Summary, MD&A, Capitalization and financial statements/notes. Takeaway: 198 words, excluding heading/source.

Encore Medical | Proposed ENMD, OTCQB
Encore Medical, Inc.’s November 16 S-1/A revises its initial public offering to 800,000–1.4 million primary shares at a proposed $5 each, targeting OTCQB quotation as ENMD. It previously contemplated 3 million shares and NYSE American. Estimated net proceeds are $2.95 million–$5.68 million; these are preliminary terms, not completed financing.
Encore develops catheter-delivered devices for cardiac septal defects and sells outside the United States. It reports approximately 35,000 implants, a company claim. It lacks U.S. marketing approval. Proceeds allocate $1.0 million–$3.5 million to a stroke trial estimated to cost $5 million, plus $1.1 million for debt repayment and $0.5 million for a GB Sciences license. Neither offering case fully funds the trial.
Nine-month September 2026 sales were $794,326, down 38.44% from the comparable period; net loss was $1.12 million. Gross margin fell to 4.18%, calculated from source dollars. Cash was $87,764. Receivable collections and payable movements supported near-breakeven operating cash flow, while the notes retain going-concern uncertainty.
Non-U.S. sales and patented device features provide an operating foundation, alongside regulatory, customer-concentration, financing and liquidity risks.
What to monitor: Minimum subscriptions, OTCQB approval, additional trial financing, clinical progress and reconciliation of capitalization/dilution tables. The best-efforts offering requires minimum subscriptions by January 31, 2027.
Sources: November 16 S-1/A, CIK 1838003, accession 0001104659-26-128582; preceding September 28 S-1/A. Cover, Use of Proceeds pp.31–39, MD&A and financial statements/notes. Takeaway: 200 words, excluding heading/source.
Meaningful update to previously covered issuers
vVARDIS Holding AG | VVVV, NYSE. The November 16 final prospectus sets the IPO at $18 per share, below the preceding $21–$24 range. Primary shares increase to 9,722,223 from 8,333,334, and the option increases to 1,458,333 from 1,250,000. Estimated issuer net proceeds are $154.5 million, or $178.9 million with the option exercised in full, versus $166.2 million at the preceding midpoint. Founder voting power is 86.9%, compared with 87.6% previously. Final pricing is disclosed; the prospectus is dated November 12 and was filed November 16. This updates the report delivered in the prior edition.
Sources: 424B4, accession 0001140361-26-043938; preceding F-1/A, accession 0001140361-26-043309.
Special Situations
Top five situations this week
UGI (UGI): Board-approved plan to spin off its LPG business and leave a stand-alone natural-gas infrastructure company, targeted for H2 2027.
TELUS (T/TU): Publicly confirmed Québecor’s unsolicited, conditional, nonbinding merger proposal and a special-committee review.
BILL (BILL): Signed $63.25-per-share cash take-private agreement at an approximate $6 billion equity value.
Vail Resorts (MTN): Oasis advanced its two-nominee campaign ahead of the December 14 shareholder vote.
Integral Acquisition 1 (INTE): Formal SPAC wind-down disclosure sets an approximately $11.61 public-share redemption, while its warrants expire worthless.
The expanded screen found qualifying new announcements or meaningful filing updates in every category. Entries do not imply a recommendation; particular attention is paid to whether a deal is proposed, signed, completed or merely disclosed in a filing this week.
1) Spin-offs & Separations
UGI Corporation (UGI / NYSE; USA) — NEW · Published/filed November 18, 2026. UGI said its board approved a plan to pursue a tax-free spin-off of its global LPG business, combining AmeriGas and UGI International in a separately listed distributor while leaving U.S. regulated gas utilities and midstream operations in UGI. Existing holders would keep their UGI shares and receive pro rata shares of the LPG company; UGI may retain as much as 19.9% initially. The split could surface sharply different valuation and capital-return profiles, but it remains a proposed transaction requiring a Form 10, lender consents and final board approval. Management targets the second half of 2027, not a guaranteed separation date.
Source
Textron (TXT / NYSE; USA) — NEW · Published/filed November 18, 2026. Textron entered a definitive agreement to sell its Industrial segment to Kingswood Capital Management for $1.2 billion and separately authorized repurchases of up to 35 million common shares. Management expects about $1.1 billion of net cash proceeds, subject to customary adjustments, with the disposal leaving a more aerospace- and defense-focused portfolio. A large new authorization is not an executed repurchase, and the segment sale is not yet closed. The transaction is anticipated to complete in the first half of 2027, subject to regulatory and other closing conditions.
Source
2) Strategic Alternatives & Reviews
Bridger Aerospace (BAER / NASDAQ; USA) — NEW · Published/filed November 16, 2026. Bridger Aerospace announced that it intends to engage a financial adviser to assess strategic alternatives while undertaking an operating reset. The company disclosed an approximately 13% workforce reduction, estimated annual savings of $5 million–$6 million, and a cut to full-year 2026 adjusted EBITDA guidance to $36 million–$39 million from $55 million–$60 million. Potential outcomes are undefined, and announcing an adviser search does not mean a sale process or binding offer exists. Any rerating thesis has to account for execution risk and the lower earnings base.
Source
Emerita Resources (EMO / TSXV; Canada) — NEW · Published/filed November 16, 2026. Canadian-listed Emerita initiated a board-led strategic review to address near-term liquidity and the valuation of its Spanish mineral interests. The menu explicitly includes new equity or royalty financing, strategic investors, project joint ventures, interests in Iberian Belt West, alternatives tied to Falcon claims and even a corporate sale. The review comes amid a requisitioned shareholder meeting and does not establish a bidder, a financing commitment or a sale price. Funding certainty, dilution and contentious governance are the immediate issues to monitor.
Source
Xtant Medical (XTNT / NYSE American; USA) — NEW · Published/filed November 16, 2026. Xtant Medical disclosed a strategic-alternatives review as it reassesses its operating outlook and capital needs. Management said possibilities may include a restructuring, raising capital, combining with another company or a sale, but offered neither a bidder nor a timetable. Investors should distinguish the option value of a transaction from a business facing execution and financing pressures. The next meaningful disclosure is a board decision or a committed transaction, neither of which has been announced.
Source
3) Substantial Buybacks, Tenders & Dividends
Insight Enterprises (NSIT / NASDAQ; USA) — NEW · Published/filed November 16, 2026. Insight disclosed that its board approved a new $400 million share-repurchase program on November 13, in addition to approximately $36.5 million remaining under previous authorizations. The November 16 SEC filing is the qualifying publication for this issue; the board decision itself preceded the window. This is a sizable capital-allocation commitment but not evidence that $400 million has already been deployed. Execution pace, available cash and the competing demands of operations and acquisitions will determine its impact.
Source
Everus Construction Group (ECG / NYSE; USA) — NEW · Published/filed November 16, 2026. Everus authorized a $100 million share-repurchase program, giving the newly independent construction-services company an additional capital-allocation lever. The announcement increases possible support for per-share value, although buybacks may be made opportunistically or not at all. Repurchase authorization is not equivalent to an open-market purchase and does not supersede operating or debt restrictions. Actual executed volumes and cash deployment are the catalysts.
Source
Keros Therapeutics (KROS / NASDAQ; USA) — NEW · Published/filed November 16, 2026. Keros authorized an additional $5 million of common-stock repurchases after receiving a $20 million Takeda development milestone, adding to its existing capital-return framework. The incremental amount is modest, but it is a concrete use-of-cash signal as investors evaluate the company’s post-restructuring asset base and remaining partnership obligations. The company reported approximately $259.5 million in cash, cash equivalents and marketable securities at September 30. The authorization does not establish the number of shares ultimately retired.
Source
Nutex Health (NUTX / NASDAQ; USA) — NEW · Published/filed November 17, 2026. Nutex declared its first public-company cash dividend, a $2.00-per-share special distribution with a November 30 record date and December 14 stated payment date. That headline cash return is unusually large on a per-share basis, but payment is explicitly conditioned on a CFO certificate to independent directors, and the board retained the right to modify or revoke it before payment. There is no binding commitment to future recurring dividends. Record-date mechanics, financing and any board update merit close attention.
Source
4) Meaningful Insider or Major-holder Purchases
Biglari Holdings / The Lion Fund (BH, BH.A / NYSE; USA) — NEW · Published/filed November 18, 2026. A November 18 Form 4 shows The Lion Fund, a vehicle controlled by Sardar Biglari, purchased 140 Class A shares and 5,303 Class B shares across November 16–17. At the filing’s disclosed prices, the purchases totaled approximately $2.15 million, and each trade is coded as a market purchase rather than a grant. They were indirect fund purchases, not direct personal purchases by Biglari, an important distinction in assessing insider conviction. The key question is whether buying continues and how these interests interact with the company’s unusual ownership structure.
Source
Berkshire Hathaway (BRK.A, BRK.B / NYSE; USA) — NEW · Published/filed November 16, 2026. A Form 4 filed November 16 disclosed that Berkshire CFO Charles Chang acquired two Class A shares on November 12, before this edition’s news window, for approximately $1.78 million in total. The holding was reported indirectly through a family-controlled entity, rather than as a freshly executed November 16 trade. This is a newly published ownership filing, not a purchase that occurred during November 14–20. It is worth monitoring for further executive buying, while recognizing that a two-share trade offers little evidence about Berkshire-wide capital policy.
Source
5) Liquidations
Integral Acquisition Corp. 1 (INTE / former Nasdaq SPAC; USA) — NEW · Published/filed November 20, 2026. Integral’s November 20 Form 8-K formally reports a board-directed wind-down after the SPAC failed to complete a business combination by its November 5 deadline. Public shares are slated for redemption at approximately $11.61 each, with the trustee instructed to liquidate trust investments on November 26 and payment expected, not guaranteed, on November 27. The warrants have expired worthless and have no redemption entitlement, while full corporate dissolution remains subject to creditor claims and other formalities. The missed November 5 deadline is background; the qualifying filing and liquidation terms were disclosed this week.
Source
6) Takeover Rumors, Reported Interest & Nonbinding Proposals
TELUS / Québecor (T / TSX, TU / NYSE; Canada) — NEW · Published/filed November 16, 2026. TELUS publicly confirmed an unsolicited, conditional and nonbinding acquisition proposal from Québecor, creating a newly disclosed takeover situation even though Québecor first approached the company in June and revised its proposal on November 9. A TELUS special committee is evaluating the offer alongside other alternatives but highlighted regulatory/spectrum obstacles, increased leverage, voting-control issues and an inadequate implied valuation. No definitive agreement or cash consideration has been announced; the proposal relies on equity and a fixed exchange ratio. The near-term catalyst is further engagement or a revised approach, with no verified shareholder vote or closing date.
Source
7) M&A, Merger Arbitrage & CVRs
BILL Holdings (BILL / NYSE; USA) — NEW · Published/filed November 19, 2026. BILL agreed to be acquired by TPG in partnership with Corpay for $63.25 per share in cash, implying an approximately $6 billion equity valuation. This is a definitive merger agreement, not a reported expression of interest, and the issuer described no financing condition. The special-situation question now centers on regulatory and shareholder approvals, the deal’s contractual protections and the eventual cash settlement rather than a speculative takeover premium. Management expects completion during the first half of 2027; no closing date or deal spread has been invented here.
Source
Aytu BioPharma (AYTU / NASDAQ; USA) — NEW · Published/filed November 16, 2026. Aytu signed a definitive agreement for Rosemont Pharmaceuticals to purchase the company for $2.70 per share in cash, or roughly $56 million on the fully diluted terms reported by the issuer. The structure calls for a tender offer followed by a second-step merger without a separate shareholder meeting once statutory conditions are met. The offer had not yet been commenced at the announcement; minimum tender participation and other merger conditions still matter. The parties expect a late-2026 closing, but a binding contract should not be confused with tender acceptance or cash payment.
Source
Rapid Micro Biosystems (RPID / NASDAQ; USA) — NEW · Published/filed November 16, 2026. Rapid Micro Biosystems entered a definitive agreement to be acquired by Merck KGaA for $0.75 per Class A share in cash, creating a small-cap tender-offer arbitrage. The tender offer had not commenced as of the announcement, and acceptance will depend on the minimum tender condition and other customary requirements. Merck is German, but the target issuer is U.S.-based, keeping the situation inside this newsletter’s coverage policy. Monitor the formal offer documents rather than assuming this signed agreement means shares have already been accepted.
Source
Viatris / Pacira BioSciences (VTRS / NASDAQ; PCRX / former NASDAQ; USA) — UPDATE · Published/filed November 17, 2026. Viatris completed its acquisition of Pacira at $36.50 per share cash on November 17, closing an arbitrage situation first announced October 8. Its tender offer expired November 16 with approximately 32.93 million shares validly tendered, or 66.46% of shares outstanding; the buyer then accepted tendered shares and completed the Section 251(h) merger without a separate shareholder vote. Remaining shares converted into the right to receive the same merger consideration. This is a close-out for the watchlist, not an actionable pending transaction or a newly announced November 17 bid.
Source
8) Activism & Proxy Contests
Vail Resorts / Oasis Management (MTN / NYSE; USA) — UPDATE · Published/filed November 16, 2026. Oasis Management escalated its existing campaign at Vail Resorts with a November 16 proxy filing and materials supporting two alternative director nominees. The activist disclosed a roughly 9.6% stake and asked shareholders to support Robert Chapek and M. Ashton Hudson at the December 14, 2026 annual meeting. A proxy fight can sharpen scrutiny of margins, governance and capital allocation, but nomination materials represent the dissident’s position, not a board-endorsed plan. The voting outcome, proxy solicitation and management response remain the key catalysts.
Source
9) Unusual Interesting Situations
Stem (STEM / NYSE; USA) — NEW · Published/filed November 16, 2026. Stem announced the sale of its Athena energy-software intellectual-property platform to Voltus for $10 million in cash, a discrete asset-monetization event amid an ongoing strategic review. Athena had generated about $14 million of revenue in 2025, so the headline proceeds need to be considered alongside revenue lost, allocated costs and any transitional obligations. The transaction reframes the residual company’s cash runway and remaining assets rather than automatically creating $10 million of incremental equity value. Monitor completion mechanics, retained liabilities and the broader strategic-review outcome.
Source
Enovix (ENVX, ENVXW / NASDAQ; USA) — UPDATE · Published/filed November 18, 2026. Enovix announced the November 18 distribution of a previously declared warrant dividend, providing one warrant for every four shares held at the November 13 record date. Each warrant permits purchase of one common share for $3.00 cash, while holders may alternatively deliver $1,000 principal of eligible 2028 convertible notes to exercise 333 warrants; separate ENVXW trading was expected November 19. The warrants have an April 28, 2028 scheduled expiry but can accelerate if the common stock reaches a specified VWAP test beginning at $3.30. This is a live capital-structure and debt-exchange situation, not a newly declared November 18 dividend.
Source
10) Other Corporate Actions
Hyperscale Data (GPUS / NYSE American; USA) — NEW · Published/filed November 20, 2026. Hyperscale filed formal tender/exchange documents offering, for each 100 common shares tendered, one Series I cumulative redeemable perpetual preferred share plus $2 cash, with up to 192.308 million common shares sought. The preferred carries a $24 liquidation preference and stated 12% yield, which must not be mistaken for $24 cash available on the exchange date; dividends do not begin accruing until 12 months after issuance, and payment still depends on the stated terms. Completion requires at least 100 million common shares tendered unless waived, with an expiration one minute after 11:59 p.m. ET on December 18, subject to extension. Illiquidity of the preferred, issuer creditworthiness and broker cutoff times dominate the economics.
Source
Upcoming catalysts
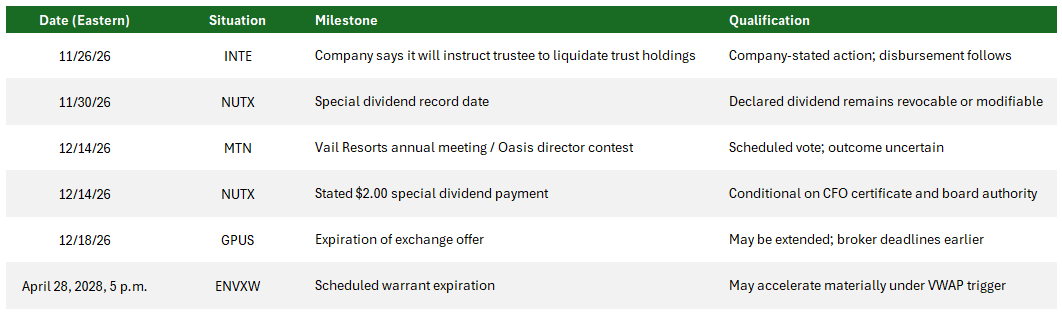
Appreciate you taking the time to read Weekly Snacks. I hope you have found at least some of these links/callouts to be interesting enough to dive into yourself.
If you haven’t already, consider hitting the subscribe button below and sharing this Substack with someone you know.
Until next week,
Paul Cerro
Weekly Snacks Twitter: @weeklysnacks
Personal Twitter: @paulcerro
Any feedback? Hit reply
Disclaimer:
Informational purposes only: This publication is provided by Weekly Snacks solely for informational and educational purposes. It is not investment advice, a recommendation to buy, sell or hold any security, or an offer or solicitation to transact in any security. It does not take into account any reader's investment objectives, financial circumstances or risk tolerance.
Independent due diligence: Each reader is responsible for conducting their own independent due diligence and evaluating the suitability and risks of any investment. This overview is a summary, not a substitute for reviewing the complete SEC filings, financial statements, risk factors and subsequent disclosures. Readers should not rely solely on this publication when making investment decisions.
Sources and limitations: Information is drawn from publicly available sources, including SEC filings, and may include company-reported figures, estimates and statements that have not been independently verified. Although care is taken in preparing this publication, its accuracy, completeness and timeliness are not guaranteed. Analysis reflects interpretations of the source materials as of the stated date and may be superseded by later filings or events.
Investment risk: Investing in securities involves risk, including the possible loss of principal. Historical financial performance, growth rates and operating metrics do not guarantee future results. IPO terms may change before pricing or completion, and an offering or exchange listing may not occur.