


Hello everyone,
Please enjoy this week’s flags for recently filed IPO prospectuses and special situations. Remember, this Substack provides quick text summaries, with a deeper 3-page overview (for IPOs) if you’d like more detail.
None of our content is meant to be taken as investment advice or validity of the proposed company/IPO.
What we cover:
Initial IPO filings
Updates from previously flagged IPOs
Special Situations based in the U.S. or CA
Upcoming catalysts
Enjoy.
This Week’s IPOs
American Barrick Gold | Proposed NYSE: ABGC
November 10, 2026 S-1.
American Barrick Gold would hold Barrick Mining’s 61.5% interest in Nevada Gold Mines and 60% interest in Pueblo Viejo in the Dominican Republic. The Nevada complex supplied 81% of attributable 2025 gold production. Existing processing infrastructure supports scale, and Fourmile adds a development opportunity subject to permitting, engineering and capital decisions.
Historical carve-out revenue rose 61.1% to $7.26 billion in the first half of 2026. Net earnings attributable to owners increased to $1.77 billion from $673 million. Consolidated operating cash flow was $3.69 billion and capital expenditures were $759 million. Higher realized gold prices were a major contributor; the historical results include parent allocations and do not establish standalone costs.
The proposed primary IPO would fund repayment of a dividend note to Barrick, with the balance for general corporate purposes. Pricing, size and the note amount are not disclosed. Barrick expects to retain majority control. Gold prices, two-joint-venture concentration and separation arrangements are material sensitivities.
What to monitor. The indicative range, public float, dividend-note amount and standalone financing terms.

Anthropic | Proposed Nasdaq Global Select Market: ANT
October 26 initial S-1; November 10, 2026 S-1/A.
Anthropic develops Claude models and sells access through its applications, APIs and cloud partners. It reports more than 11,900 customers with at least $100,000 of trailing annual revenue at September 30, up from more than 950 a year earlier. Distribution through several channels and adoption in enterprise workflows support usage growth.
Revenue was $33.24 billion for the nine months ended September, versus $2.55 billion a year earlier. The operating loss narrowed to $1.26 billion from $5.22 billion; the $104.04 billion net loss included $94.32 billion of fair-value losses on notes, derivatives and SAFEs. Operating cash flow was $6.57 billion and purchases of property and equipment were $925 million, excluding lease and equipment prepayments.
The amendment proposes $70–$78 for 801.35 million primary and 23.65 million secondary shares. Anthropic estimates $84.6 billion combined net issuer proceeds at $74, including a separate $26 billion placement. Uses include infrastructure, staffing and employee equity tax withholding. The Founder LLC retains majority general voting power; compute supply and model competition are material risks.
What to monitor. Final pricing, placement closing, dilution and infrastructure spending relative to revenue.
Focus Media Network | Proposed Nasdaq Capital Market: FMSN
October 28 initial F-1; November 9, 2026 F-1/A.
Focus Media Network is a Cayman issuer with two Singapore operating subsidiaries. It sells advertising through a digital display network it says spans more than 800 screens at more than 500 locations. A broad venue footprint supports advertiser reach, while access to sites, lease costs and advertiser retention affect network economics.
For the year ended March 2026, revenue rose to S$4.63 million from S$2.27 million. Net income of S$2.93 million included a S$738,610 tax benefit, compared with a prior-year loss of S$215,293. Operating cash flow was S$920,443 and capex was S$27,150. The two largest customers accounted for 28% of revenue.
The issuer proposes five million primary shares at an indicative US$4–US$6. Estimated net proceeds of US$22 million at the midpoint would fund screens, software, partnerships or acquisitions, regional development and working capital. The amendment adjusts the historical share base from 10 million to 15 million, revising FY26 EPS to S$0.195 from S$0.293 without changing net income or relative ownership.
What to monitor. Final price, Nasdaq approval and cash conversion as the screen network expands.
Simwon America | Proposed Nasdaq Global Market: SWA
October 9 initial S-1; November 6, 2026 S-1/A.
Simwon America makes precision structural components for vehicle bodies. Its U.S. production capabilities include stamping and hot forming. Automaker qualification and localized production support continuity on existing programs, but Tesla accounted for 99.02% of FY2026 sales and generally has no minimum purchase commitments.
For the fiscal year ended June, revenue fell 13.2% to $323.85 million while gross margin increased to 10.6% from 8.1%. Net income rose to $16.93 million from $11.27 million. Operating cash flow increased to $32.35 million, aided by working capital movements, and capital expenditures declined to $4.15 million.
The amended offer covers 1.5 million primary and one million secondary shares at an indicative $18–$22. The company estimates $23.9 million net at $20 for a potential East Coast acquisition, Canada and Mexico expansion, independent R&D and working capital. South Korea’s Simwon Tech would retain 80.54% voting control at base closing; the issuer relies on related parties for procurement and technology.
What to monitor. Final price, listing approval, any acquisition terms and revenue from customers other than Tesla.
Material updates to tracked issuers
Rezera (proposed RZRA) — November 9. Estimated offering expenses excluding underwriting discounts increased to $5.05 million from $4.09 million. The indicative $11–$13 range, 16,666,667 primary shares and estimated $181.0 million net proceeds at $12 were unchanged. Blue Owl’s revised table position is 4.80% before an exchange into non-voting shares; the post-exchange 4.50% voting cap remains. SEC amendment · Prior prospectus
vVARDIS (proposed VVVV) — November 12. Base primary shares fell to 8.33 million from 9.52 million. A 1.25 million-share issuer option replaced a 1.43 million-share seller option. The indicative $21–$24 range was unchanged; estimated base net proceeds fell to $166.2 million from $191.1 million at the midpoint. Founders’ estimated voting power increased to 87.6% from 87.0%. SEC amendment · Prior prospectus
Special Situations
Top five situations this week
Surgery Partners (SGRY): A signed going-private deal gets bumped to $25 cash from $23.50, with a contingent ticking fee if the vote has passed and the deal is delayed beyond March 1.
Western Union / Intermex (WU / IMXI): A would-be acquisition turns into a disputed termination, following contested California regulatory conditions.
Strathcona / Greenfire (SCR / GFR): A Canadian oil-sands deal gives holders C$11 cash or 0.25 SCR shares without proration, alongside related-party minority-vote mechanics.
Helen of Troy (HELE): The public fight over Empower’s nonbinding $37 cash proposal intensifies even as the target rejects it.
GFL Environmental (GFL): The board formally ends its take-private review and chooses the public-company route, extinguishing the near-term auction thesis.
1. SPIN-OFFS & SEPARATIONS
Barrick Mining / American Barrick Gold (NYSE: B; TSX: ABX; Canada) — NEW (2026-11-10). Barrick filed an S-1 for American Barrick Gold, the proposed NYSE-listed minority IPO vehicle for its North American gold assets, including interests in Nevada Gold Mines and Pueblo Viejo. Barrick expects to retain majority control, so this is not a direct share distribution to Barrick stockholders. An IPO could sharpen the value of the North American portfolio, but the share count, offering price and launch timing remain undetermined and SEC review must run its course.
KBR / Trinzic (NYSE: KBR; anticipated TZIC; US) — UPDATE (2026-11-11–12). KBR and planned spin-off Trinzic held investor days describing the future standalone engineering and mission-technology companies, following a fresh Form 10 amendment and board-designate disclosures. Trinzic presented a business with more than $5 billion in annual revenue, while remaining KBR outlined a separate organic-growth framework. The separation remains targeted for January 4, 2027, subject to final board approval and other conditions; neither the listing nor the re-rating is assured.
Keurig Dr Pepper (NASDAQ: KDP; US) — NEW (2026-11-12). Keurig Dr Pepper priced 57,971,015 newly issued shares at $34.50, raising roughly $2 billion before fees as it prepares to separate its coffee and refreshment-beverage businesses. The proceeds are intended for debt reduction ahead of the contemplated two-company structure, and underwriters have an additional-share option. Closing of the offering was expected November 16, while the broader separation is targeted for early 2027; dilution, leverage and execution of the split remain the moving pieces.
2. STRATEGIC ALTERNATIVES & REVIEWS
Xcel Brands (NASDAQ: XELB; US) — NEW (2026-11-09). Xcel Brands said it is exploring strategic alternatives for noncore legacy brands and intellectual property, potentially including divestitures. The development matters because brand-level proceeds could simplify the portfolio and relieve capital needs without necessarily requiring a whole-company sale. Management has not disclosed a buyer, price or timetable, so any estimate of monetization value remains speculative.
TransAct Technologies (NASDAQ: TACT; US) — UPDATE (2026-11-12). TransAct broadened its existing review of the Casino and Gaming operation to include possible alternatives for its Food Service Technology segment, raising the prospect of a division sale or a wider transaction. Its preliminary third-quarter disclosure put each segment at approximately $6.4 million in revenue, making the mix and separation economics material to any valuation. The company has not agreed to a sale and offered no process deadline; the biggest risk is that neither division attracts a price that justifies a transaction.
GFL Environmental (NYSE/TSX: GFL; Canada) — UPDATE (2026-11-10). GFL formally ended its special-committee review of unsolicited take-private proposals and said its board unanimously favors remaining publicly listed. The committee acknowledged that offers carried premiums to the trading price but judged standalone free-cash-flow and margin opportunities more attractive; it also noted continued third-party interest in some financial sponsors’ stakes. This closes the prior whole-company sale-review thesis for now, although future sponsor-block transactions could still influence the stock.
Longeveron (NASDAQ: LGVN; US) — NEW (2026-11-12). Longeveron launched a strategic-alternatives review with Lucid Capital that could encompass financing, partnerships, an asset transaction or a corporate sale following developments in its cell-therapy portfolio. The process provides a potential financing or monetization catalyst for a development-stage biotech, but no party or terms were disclosed. Cash runway and future trial funding remain central downside risks, and the review itself carries no commitment to a deal.
Innventure (NASDAQ: INV; US) — UPDATE (2026-11-12). Innventure’s latest 10-Q added tangible restructuring steps to the strategic review already on our watchlist: it disclosed a November agreement to divest Vital1 using a secured promissory-note structure and a decision to stop funding AeroFlexx. The review of portfolio funding and commercialization options continues as the company works toward planned Refinity financing by year-end. These actions may reduce cash demands but also introduce collectability, related-party and execution risks; the review itself was not newly initiated this week.
3. BUYBACKS, TENDERS & DIVIDENDS
Kontoor Brands (NYSE: KTB; US) — NEW (2026-11-11). Kontoor entered into a $400 million accelerated share-repurchase agreement under an existing $750 million authorization, rather than merely increasing an unused ceiling. It expected an initial share delivery around November 12 and final settlement in the first half of 2027, so the final share reduction depends on the contract’s averaging mechanism. Following portfolio reshaping, the size and immediacy of the ASR make it more actionable than a routine authorization, although leverage and final execution still matter.
Steel Dynamics (NASDAQ: STLD; US) — NEW (2026-11-09). Steel Dynamics approved a new $3 billion share-repurchase authorization and reaffirmed its quarterly cash dividend, a substantial capital-return signal for a cyclical producer. The additional authorization expands capacity but is not an executed purchase and carries no guaranteed drawdown schedule. Steel prices, capital needs and management’s buyback cadence will determine how much of the stated capacity actually retires shares.
John B. Sanfilippo & Son (NASDAQ: JBSS; US) — NEW (2026-11-12). John B. Sanfilippo authorized a $20 million common-share buyback and declared a $2.00-per-share special dividend across its voting classes. The dividend has a record date of December 4 and payment date of December 18, providing a hard-dated cash-return catalyst rather than just an open-ended board authorization. The buyback remains discretionary, and investors should distinguish the special distribution from recurring earnings power.
Thomson Reuters (NYSE/TSX: TRI; Canada) — NEW (2026-11-11). Thomson Reuters announced a $500 million normal-course issuer bid covering up to seven million shares, approximately 1.6% of outstanding stock, beginning November 13. With Woodbridge controlling a majority stake, repurchases may change the effective public float more than the headline percentage implies. The bid’s scheduled authorization period ends November 12, 2027, but shares are acquired only if management actually buys them.
4. INSIDER & MAJOR-HOLDER PURCHASES
Starwood Property Trust (NYSE: STWD; US) — NEW (2026-11-13). A Form 4 filed at 9:19 p.m. Eastern on Friday disclosed purchases totaling 1,245,000 shares on November 11–12 in accounts associated with CEO Barry Sternlicht, representing roughly $14.7 million using reported transaction prices. The reported ownership was through a charitable foundation, an important distinction from an outright purchase held in his own name. These are coded open-market purchases, not equity grants, but the indirect holding arrangement and mortgage-credit exposure complicate a simple insider-alignment interpretation.
MP Materials (NYSE: MP; US) — NEW (2026-11-12). MP Materials disclosed two separate November 10–11 code-P insider transactions: director Randall Weisenburger bought 55,000 shares at about $36, while operating executive Michael Rosenthal purchased 32,000 shares across several prices. The combined reported spending was approximately $3.2 million, a more meaningful signal than stock awards or option exercises. Both transactions were subsequently reported on Form 4; commodity, policy and project-execution risks still dominate the economic thesis.
FTAI Infrastructure (NASDAQ: FIP; US) — NEW (2026-11-12). FTAI Infrastructure CEO Kenneth Nicholson reported a 400,000-share purchase on November 10 at a weighted average of $3.825, or roughly $1.53 million. The Form 4 uses transaction code P and reports direct ownership after the transaction, distinguishing the purchase from vesting or a compensation grant. The size is relevant against the company’s capital-intensive infrastructure strategy, but financing and asset-performance risks remain central.
5. LIQUIDATIONS
Winvest Acquisition Corp. (OTC: WINV / WINVW; US) — NEW (2026-11-12). Winvest and counterparties terminated their proposed combination with Embed Financial, abandoning the previously agreed de-SPAC transaction. At the same time, Winvest disclosed another $30,000 sponsor deposit extending its business-combination deadline from November 17 to December 17, 2026, rather than announcing immediate liquidation. The trade is a trust-redemption and sponsor-extension watch, not an already declared liquidation; remaining public-share rights and warrant treatment require careful review.
6. TAKEOVER INTEREST, RUMORS & NONBINDING PROPOSALS
Helen of Troy / Empower Brands (NASDAQ: HELE; NYSE: SPB; US) — UPDATE (2026-11-12). Helen of Troy reiterated that its board unanimously rejected Empower Brands’ unsolicited, nonbinding $37-per-share cash proposal, while Empower—backed by Spectrum Brands and Oaktree—published a fresh open letter urging shareholders to press for engagement. Empower puts the implied enterprise value at roughly $1.6 billion and says an affiliate owns about 4.5% of HELE, intensifying the public pressure campaign. There is no signed merger agreement, no tender, and no closing timetable; the important variables are whether the bidder improves terms or the board can defend standalone execution.
LCI Industries / Monomoy Capital (NYSE: LCII; US) — UPDATE (2026-11-10). LCI disclosed a revised $104.50-per-share nonbinding cash proposal from Monomoy Capital while LCI remains under a signed merger agreement with Patrick Industries. Its board judged the rival bid neither superior nor reasonably likely to lead to a superior proposal, leaving the Patrick transaction as the operative agreement. The unusual setup creates a rival-bid option, but the revised proposal is not a binding offer and LCI shareholders still face the original deal’s vote, regulatory and closing conditions.
The RealReal (NASDAQ: REAL; US) — NEW — UNCONFIRMED REPORT (2026-11-13). A November 13 report claimed that an unidentified activist had accumulated a significant stake in The RealReal and was pressing the board to explore a sale; it also suggested a banker might be involved. Neither the activist’s identity, ownership level nor a board-led sale process was corroborated by a contemporaneous issuer release or 13D in this review, so this is an investigative lead, not a confirmed campaign or bid. Verification of the underlying reporting and any subsequent filing is essential before implying that a transaction is underway.
7. M&A, MERGER ARBITRAGE & CVRs
Strathcona Resources / Greenfire Resources (TSX: SCR / TSX, NYSE: GFR; Canada) — NEW (2026-11-08). Strathcona signed a definitive arrangement to acquire Greenfire with either C$11.00 cash or 0.25 Strathcona share per Greenfire share, at each holder’s election without proration. Waterous Energy Fund owns roughly 72% of Greenfire and 57% of Strathcona and has agreed to take the stock election, making minority approvals and related-party governance particularly important. The companies described an enterprise value of C$2.7–2.9 billion on November 6 reference prices and anticipate January 2027 shareholder meetings followed by closing, subject to minority, court and regulatory approvals.
Surgery Partners / HealthSpan (NASDAQ: SGRY; US) — UPDATE (2026-11-09). Surgery Partners amended its signed going-private agreement, increasing the cash merger price from $23.50 to $25.00 per share. If shareholder approval has been obtained but the merger has not closed by March 1, 2027, the contract adds a 10% annualized ticking fee on the $25 base, capped at $1.61 per share under the outside date. The richer terms improve merger-arbitrage economics, but stockholder approval, regulatory clearance and any competing bids remain material conditions.
International Money Express / Western Union (NASDAQ: IMXI; NYSE: WU; US) — UPDATE (2026-11-10–12). Western Union said it terminated its previously signed acquisition of International Money Express after California regulators offered conditions it regarded as unacceptable at the merger’s November 10 outside date. Intermex disputes the termination, says relevant conditions had been satisfied or frustrated by Western Union, and reserves the right to seek specific performance or damages. This should be treated as a failed or contested merger, not an ordinary pending cash deal at the old transaction price; litigation and standalone valuation now dominate.
Heron Therapeutics / CorMedix (NASDAQ: HRTX; NASDAQ: CRMD; US) — NEW (2026-11-09). CorMedix agreed to acquire substantially all of Heron’s assets for $145 million cash plus 14,583,333 CorMedix shares, with up to $55 million of sales-contingent payments and additional royalties. The stock portion was worth approximately $77.6 million using November 6 prices, but Heron itself is not being merged out for a fixed per-share cash price: its residual company retains the transaction proceeds and obligations. The parties target first-quarter 2027 closing, subject to Heron shareholder and other approvals, while earnout collection and residual-company value are major underwriting variables.
Hancock Whitney / Trustmark (NASDAQ: HWC / NASDAQ: TRMK; US) — NEW (2026-11-12). Hancock Whitney signed an all-stock agreement to acquire Trustmark for 0.7463 HWC share per TRMK share, valuing the target at roughly $3.2 billion using November 11 trading prices. Trustmark owners would hold about 35% of the combined bank, and management targets the latter part of first-quarter 2027 for completion. With consideration floating alongside HWC shares, the right analysis is a hedge-ratio and bank-regulatory study rather than treating the announcement-date dollar value as guaranteed proceeds.
Utz Brands / Intersnack (NYSE: UTZ; US) — UPDATE (2026-11-13). Utz reported that shareholders approved its previously announced sale to an Intersnack-related buyer at a November 13 special meeting, based on preliminary voting results. Management now expects the merger to close on or around November 20, subject to the remaining conditions; shareholder approval itself is not closing. The vote removes an important hurdle for merger arbitrage, but investors still need to confirm the final tally, consummation and final treatment of transaction-related adjustments.
8. ACTIVISM & PROXY CONTESTS
First Internet Bancorp / John C. Lame (NASDAQ: INBK; US) — NEW (2026-11-13). A Friday-evening Schedule 13D amendment disclosed a 5.13% position held across John and Susan Lame-related accounts and a Rule 14a-8 proposal asking independent directors to hire a banker to evaluate a possible sale. The proposal seeks reporting of the review’s findings by December 31, 2027, and is intended for the 2027 annual meeting; neither the shareholder vote nor a board-led auction has occurred. The holders reported no purchases in the preceding 60 days, so this is an activist governance development, not fresh insider buying.
9. UNUSUAL INTERESTING SITUATIONS
Braemar Hotels & Resorts (NYSE: BHR; US) — NEW (2026-11-10). Braemar completed the termination of its external advisory relationship with Ashford and transitioned to a self-managed REIT, together with a reshaped board and governance structure. The change can materially alter fee leakage, decision rights and the company’s valuation relative to externally managed lodging peers, but it also brings transition obligations and execution costs. The filing describes the restructuring as completed on November 10, not merely a proposed strategic review, and the company expects a residual project-management arrangement to end in first-quarter 2027.
10. OTHER CORPORATE ACTIONS
Dana (NYSE: DAN; US) — NEW (2026-11-13). Dana reported acceptance of approximately $357.9 million principal amount of its 2030 and 2032 notes under tender offers that expired at 5 p.m. Eastern Friday. Consideration was reported at $975.28 and $976.35 per $1,000 principal, respectively, plus accrued interest, with November 17 settlement anticipated. The company also reserved the ability to remove or defease certain covenants on remaining notes, creating different economics for participating holders and holdouts; acceptance is distinct from actual payment.
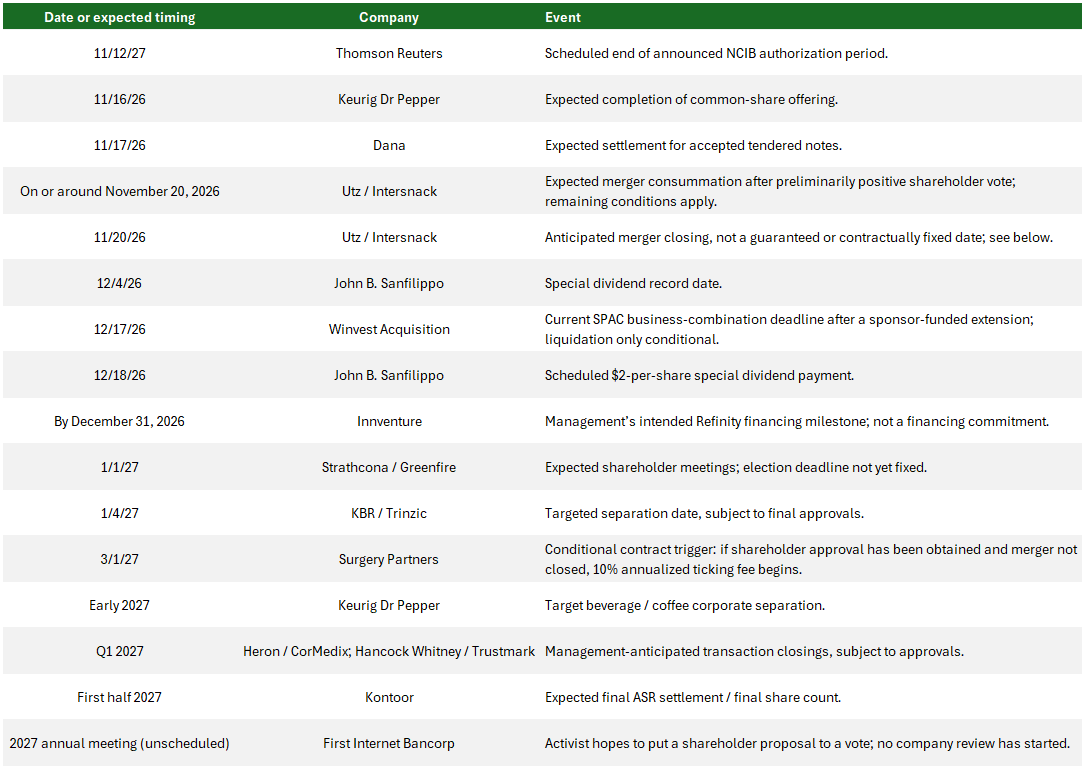
Upcoming catalysts
Appreciate you taking the time to read Weekly Snacks. I hope you have found at least some of these links/callouts to be interesting enough to dive into yourself.
If you haven’t already, consider hitting the subscribe button below and sharing this Substack with someone you know.
Until next week,
Paul Cerro
Weekly Snacks Twitter: @weeklysnacks
Personal Twitter: @paulcerro
Any feedback? Hit reply
Disclaimer:
Informational purposes only: This publication is provided by Weekly Snacks solely for informational and educational purposes. It is not investment advice, a recommendation to buy, sell or hold any security, or an offer or solicitation to transact in any security. It does not take into account any reader's investment objectives, financial circumstances or risk tolerance.
Independent due diligence: Each reader is responsible for conducting their own independent due diligence and evaluating the suitability and risks of any investment. This overview is a summary, not a substitute for reviewing the complete SEC filings, financial statements, risk factors and subsequent disclosures. Readers should not rely solely on this publication when making investment decisions.
Sources and limitations: Information is drawn from publicly available sources, including SEC filings, and may include company-reported figures, estimates and statements that have not been independently verified. Although care is taken in preparing this publication, its accuracy, completeness and timeliness are not guaranteed. Analysis reflects interpretations of the source materials as of the stated date and may be superseded by later filings or events.
Investment risk: Investing in securities involves risk, including the possible loss of principal. Historical financial performance, growth rates and operating metrics do not guarantee future results. IPO terms may change before pricing or completion, and an offering or exchange listing may not occur.