


Hello everyone,
Please enjoy this week’s flags for recently filed IPO prospectuses and special situations. Remember, this Substack provides quick text summaries, with a deeper 3-page overview (for IPOs) if you’d like more detail.
None of our content is meant to be taken as investment advice or validity of the proposed company/IPO.
What we cover:
Initial IPO filings
Updates from previously flagged IPOs
Special Situations based in the U.S. or CA
Upcoming catalysts
Enjoy.
This Week’s IPOs
SB Energy, Inc.
SB Energy, Inc. (CIK 2133037) develops power infrastructure and data centers for large computing customers. Its September 21 S-1/A proposes SBE on Nasdaq Global Select Market and Nasdaq Texas; the IPO has been reported postponed, and current SEC records and issuer announcements did not identify a formal withdrawal or cancellation through November 6. The schedule remains unresolved.
Price, public share count, and net proceeds are not disclosed. Proposed funding includes public shares and a contemplated NVIDIA investment, with uses including related-party obligations, infrastructure development and general corporate purposes. The historical consolidated business, formerly SE Global Holdings, LLC, reported H1 2026 revenue of $138.659m, a $3.192bn net loss, $55.597m operating cash outflow and $1.672bn cash capex. Large warrant and compensation charges explain much of the accounting loss; they do not remove construction funding needs.
Contracted power assets, sites and project access support the development platform. Data-center leases had not commenced as of June 30, while construction, grid access, related-party tenants and financing remain material risks. Company backlog estimates are not revenue or profit.
What to monitor: Rescheduled offering disclosures, financing commitments, energization and tenant commencement milestones, and final price, capitalization, and proceeds allocations.
Source: S-1/A filed September 21, 2026; accession 0001628280-26-062846.

Substantive Updates to Included Coverage
Rezera: preliminary terms added
The November 5 S-1/A proposes 16,666,667 primary shares at $11–$13, with a 2.5m-share option. Estimated net proceeds are $181.0m at the $12 midpoint, or $208.9m with the full option; final pricing remains undisclosed. The November 4 reverse split restates share counts and EPS, without changing historical dollar losses. Proposed Nasdaq Global Market ticker: RZRA. The proceeds support ruvonoflast Phase III development and general purposes; the company projects funding into Q1 2029, while additional capital is needed for other programs. The GSK agreement exhibit-index date is inconsistent with the filing date, so exact execution timing remains unresolved; no execution-date claim is made here.
Source: 0001104659-26-122953.
LIS Technologies: larger preliminary offering
The November 5 S-1/A increases primary shares to 3.1m from 2,833,334 and the option to 465,000 from 425,000. The $5–$7 range and proposed Nasdaq Capital Market ticker LIS are unchanged. At the $6 midpoint, estimated net proceeds rise to $16.6m from $15.1m, or $19.2m from $17.5m with the full option. No final price is disclosed.
Source: 0001493152-26-050287.
Georgia Banking Company: Q3 earnings and credit update
The November 6 presentation (also furnished with Form 8-K) reports the first full combined quarter with Tandem: GAAP net income $6.263m versus $5.621m in Q2, diluted EPS $0.57, and net interest income $31.419m versus $29.089m. Net interest margin declined to 4.17% from 4.31%; credit-loss/unfunded-commitment provision increased to $2.019m from $1.104m. CET1 was 10.59%; nonperforming assets were 0.70% of assets. Company-defined operating EPS of $0.74 is non-GAAP, excluding $1.954m direct-listing and $0.493m acquisition expenses, net of $0.636m tax effects. The October 30 selling-holder supplement is not a new capital raise. Nasdaq Capital Market: GBC.
Source: 0001104659-26-123604.
Aspen Neuroscience: beneficial ownership disclosures
November 6 ownership filings show Gilead at 2,879,996 shares (9.9%), compared with 1,666,663 (5.7% post-offer) in the final prospectus table excluding possible IPO purchases; the 13G does not establish how the increase was acquired. OrbiMed reports 3,589,132 shares (12.3%), including a disclosed IPO purchase of 1m shares at $15, versus 2,589,132 (8.9%) in that table. These disclosures do not revise offering terms. Nasdaq Global Select Market: ASPE.
Source: 0001123292-26-001496. OrbiMed Schedule 13D.
KiNRG: governance and key-person changes
The November 5 amended 8-K identifies three departures of directors described as independent in the preliminary prospectus, including two named audit committee members, alongside replacement committee leadership and a COO. It corrects the original report: Wallen resigned as KiNRG president, retired as Trinity CEO and remains an adviser; his action is not a fourth board departure. No revised offering terms or finding of listing noncompliance is disclosed.
Source: 0001213900-26-116442.
Special Situations
1. SPIN-OFFS & SEPARATIONS
CVS Health (CVS US) — NEW (November 4). CVS announced plans to split into two publicly traded companies, effectively unwinding its vertically integrated healthcare model. One company will retain Aetna, CVS Caremark, CVS Specialty, Oak Street Health, and Signify Health, while the other will house approximately 9,000 CVS pharmacies, MinuteClinic, mail pharmacy, and Health100. The separation is expected to be tax-free to shareholders and completed in the first half of 2028. This is a particularly interesting situation given the vastly different business models, margin profiles, and capital requirements of the two entities, potentially allowing investors to value each independently. Shares fell sharply on the announcement, so it’ll be worth watching whether the market eventually assigns a higher combined valuation to the two standalone businesses. The deal still requires final board approval and regulatory filings.
KBR (KBR US) — UPDATE (October 29). KBR continues progressing toward spinning off its Mission Technology Solutions business into an independent public company named Trinzic (expected ticker: TZIC). The separation is targeted for January 4, 2027, and will leave behind a more focused KBR centered on sustainable technology solutions. The interesting angle is the substantially different customer bases and valuation profiles of the two businesses, particularly Trinzic’s exposure to defense, national security, and space. Investor Days scheduled for November 11 and 12 should provide more clarity on the standalone financial profiles.
National Fuel Gas (NFG US) — UPDATE (November 4). National Fuel is progressing with plans to separate its upstream and gathering operations into a standalone public company called Seneca Resources, leaving the remaining company as a fully regulated natural gas utility and infrastructure business. The separation, originally announced in October, is expected in the second half of 2027, with shareholders receiving at least 80.1% of Seneca and National Fuel retaining up to 19.9%. This could be interesting given the different valuation multiples assigned to regulated utilities versus natural gas exploration and production businesses.
2. STRATEGIC ALTERNATIVES & REVIEWS
Innventure (INV US) — UPDATE (November 2). Innventure formed an independent strategic review committee as the parent company wrestles with a near-term liquidity squeeze. The company has cut headcount from 40 to 15 since the end of Q1 and is considering its at-the-market equity program while pursuing financing for its operating subsidiaries. The distinction between cash held at a subsidiary and cash available to the parent looks especially important here; investors should watch whether a financing or asset-level transaction can bridge the gap without punitive dilution.
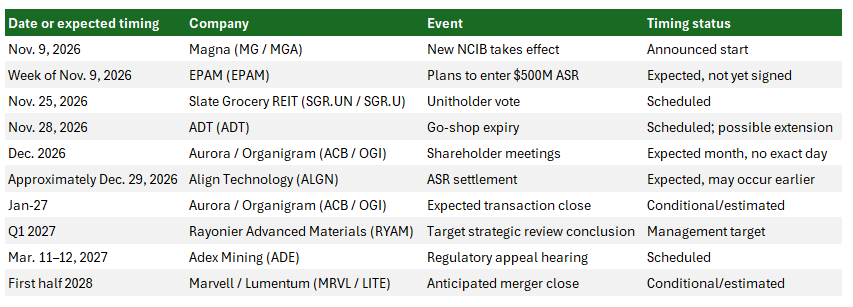
Rayonier Advanced Materials (RYAM US) — UPDATE (November 3). RYAM is still in discussions with interested parties about strategic alternatives, but the process has slowed because U.S. tariffs and the economic idling of its Temiscaming operation are complicating valuation. Management now targets a conclusion in Q1 2027 rather than an immediate transaction. Its higher-value cellulose franchise remains the obvious asset to underwrite, but the commodity exposure, $221 million of quarterly noncash impairments, and Canadian operating uncertainty make this far from a clean break-up story.
Onterris (ONT US) — UPDATE (November 4). Environmental-services company Onterris says its board-led strategic review remains active and that it has engaged several strategic and financial parties, with Evercore and AEC advising. The timing is interesting because the company is also integrating tuck-in acquisitions and reported $35.9 million of quarterly adjusted EBITDA at a 17.7% margin. A whole-company transaction or portfolio action is possible, but nothing has been agreed and management has not given a review deadline.
Monro (MNRO US) — NEW (November 4). Monro extended the expiration of its shareholder rights plan by almost a year, from November 6, 2026 to November 1, 2027, specifically to protect its ongoing review of strategic alternatives. That is not a new sale offer, but it suggests the process remains unfinished and management wants more room to evaluate potential approaches. The obvious counterpoint is that the extended rights plan could also make an unsolicited acquisition harder, so the next meaningful disclosure will be whether an actual transaction emerges.
Adex Mining (ADE CN) — UPDATE (November 6). The Canadian junior miner postponed a regulatory appeal over its Mount Pleasant mineral claim from early December to March 11–12, 2027, while its special committee continues to explore a value-maximizing transaction for the project. The claim was previously cancelled by the regulator but reinstated temporarily pending the appeal, which makes the legal status of the asset fundamental to any bid. More time may help negotiations, but shareholders are effectively underwriting both a legal outcome and a potential asset transaction.
3. NOTABLE BUYBACKS, TENDERS & CAPITAL RETURNS
Frontdoor (FTDR US) — UPDATE (November 5). Home-warranty provider Frontdoor announced another $1 billion share-repurchase authorization after buying back $259 million of shares through September. Management expects to finish the previous authorization in November, and its $298 million of year-to-date free cash flow gives the new program some operating support. This one is worth watching for an actual reduction in diluted shares rather than merely a large authorization headline.
Dynatrace (DT US) — UPDATE (November 3). The company authorized an additional $1 billion of repurchases, to begin once its previous February 2026 program is used up. The new authorization has no expiry and will be funded from cash and future cash flow. Investors should distinguish the authorized amount from cash actually deployed; the relevant future test is whether capital returns offset dilution and improve per-share economics.
EPAM Systems (EPAM US) — NEW (November 5). EPAM unveiled a $1.8 billion total share-repurchase program, replacing its earlier authorization, and intends to enter a $500 million accelerated repurchase during the week of November 9. The company also committed to returning at least 50% of annual free cash flow from 2027 through 2029. That is a more concrete capital-return framework than a routine authorization, although the accelerated program still needs to be executed and some funding may come from its credit facility.
Align Technology (ALGN US) — NEW (November 6). Align signed a $270 million accelerated share-repurchase agreement with Goldman Sachs under its existing $1 billion buyback authorization. Unlike a fresh board authorization, this is a funded contractual repurchase: Align will prepay the bank, with final shares determined largely by the VWAP during the program. Management expects completion around December 29 and about $330 million of remaining authorization afterward, so the final share count and average price are the numbers to track.
Atmus Filtration Technologies (ATMU US) — NEW (November 6). Atmus replaced its previous $150 million repurchase program with a fresh $300 million authorization; the old program still had $28.9 million of unused capacity. The filtration supplier generated $88 million of adjusted free cash flow in Q3 and repurchased $20 million of shares during the quarter. We like the combination of cash generation and buyback capacity, but the $300 million is a replacement—not an additional $300 million on top of the old program—and management has not committed to a timetable.
Magna International (MG CN / MGA US) — NEW (November 5). Magna renewed its normal course issuer bid, allowing purchases of as many as 25.78 million shares, or roughly 10% of the public float, between November 9, 2026 and November 8, 2027. The important wrinkle: the company had already exhausted the prior 25.3 million-share program, providing a better execution record than most headline authorizations. Repurchases remain discretionary and some shares may be used for compensation programs rather than cancelled.
4. INTERESTING INSIDER & LARGE PURCHASES
Kinder Morgan (KMI US) — NEW (November 6). Executive chairman Richard Kinder purchased 500,000 shares in the open market at a reported weighted-average price of $29.99, an investment of roughly $15 million disclosed in a Friday-evening Form 4. These are transaction-code P purchases, not equity grants or option exercises. The purchase is sizable in absolute dollars, although it is small relative to his already enormous existing stake, so it is better viewed as a conviction signal than a standalone catalyst.
5. LIQUIDATIONS
No qualifying new or material updated situation selected for this edition.
6. REPORTED INTEREST & NONBINDING TAKEOVER PROPOSALS
Wendy’s (WEN US) — NEW (November 5). Wendy’s independent committee rejected the Trian-led consortium’s $7.35-per-share cash proposal to buy the shares it doesn’t already own, saying the offer undervalues the company’s turnaround plan. The board also adopted a one-year shareholder rights plan with a 15% ownership trigger, effectively making an unsolicited accumulation harder. This now looks like a contest between the value of a messy franchise turnaround and the willingness of an already influential shareholder group to raise its price; there is no agreed transaction.
Dine Brands Global (DIN US) — UPDATE (November 2–3). Arkhouse and Cobblers Cove disclosed an unsolicited $39-per-share cash proposal for the Applebee’s/IHOP parent, which Dine’s board rejected on October 29. The bidders replied on November 2 that access to management and diligence might justify a higher price, but this remains a nonbinding approach rather than a financed, agreed sale. The possibility of an improved bid is the attraction here; board resistance and the absence of a definitive transaction are the obvious risks.
EVgo (EVGO US) — UPDATE (November 2). LS Power, already controlling about 56% of EVgo’s voting power, offered $2.00 per share in cash for the remaining publicly held Class A shares. The board formed a special committee to evaluate the preliminary, nonbinding proposal. Minority shareholders are now essentially betting on what the committee concludes is fair value, with related-party conflicts and the possibility of no deal making this different from a conventional announced merger-arb spread.
7. M&A / MERGER ARBITRAGE
Aurora Cannabis / Organigram (ACB CN / OGI CN) — UPDATE (November 3). Organigram agreed to acquire Aurora at an implied C$7.80 per share while Aurora is already subject to a rival Curaleaf approach. Aurora holders can elect C$7.80 cash, 5.8626 OGI shares, or C$3.75 plus 3.0431 OGI shares, but the cash and share elections are subject to aggregate limits and proration. The competing-bid angle is interesting, yet the stock election means C$7.80 should not be treated as a guaranteed cash payout; shareholder meetings are expected in December and closing in January.
ADT (ADT US) — UPDATE (October 29). ADT signed a $10-per-share cash buyout with Thrive Holdings, valuing the security company at approximately $15.3 billion of enterprise value. The 30-day go-shop runs through November 28, with a possible extension for qualifying bidders, so there remains a window for a topping offer. Financing commitments have been provided by Apollo-managed funds and the deal has no financing condition, although antitrust and shareholder approvals are still required before the anticipated Q1 2027 close.
Marvell / Lumentum (MRVL US / LITE US) — UPDATE (November 2). Marvell agreed to acquire Lumentum in a fixed-ratio all-stock transaction giving each LITE share 4.500 MRVL shares. The companies announced an implied $115 billion enterprise value and expect Lumentum holders to own roughly 33% of the combined company. The long projected closing window—first half of 2028—leaves investors exposed to Marvell’s share price, antitrust review and the risks of a very large integration rather than a simple cash takeover.
Slate Grocery REIT (SGR.UN CN / SGR.U CN) — UPDATE (November 2). Slate mailed the circular for its proposed sale to a Brixmor/Everview joint venture at US$13 cash per unit, equivalent to an announced enterprise value of about US$2.3 billion. The special unitholder vote is set for November 25, bringing the deal into the final approval phase rather than leaving it as a strategic-review rumor. A cash price simplifies the arithmetic, but completion still depends on the required approvals and satisfaction of closing conditions. Source
Silver47 / Bunker Hill (AGA CN / BNKR CN) — UPDATE (November 6). The merger has now closed, with former Silver47 holders receiving 0.1724 Bunker Hill shares for each AGA share. The combined company issued 36.3 million new Bunker Hill shares and former Silver47 investors own approximately 43% of the combined shares outstanding on an undiluted basis. That closes the merger-arbitrage event; any future investment case is now about the post-merger mining portfolio, share liquidity and execution rather than a remaining deal spread. Source
8. ACTIVIST ACTION
People Incorporated (PPLI US) — NEW (November 5). Arkhouse pressed Barry Diller’s People Incorporated to repurchase at least $750 million of stock through a Dutch auction, monetize its New York headquarters and give shareholders contingent value rights tied to its litigation against Alphabet. The activist argues that a nearly debt-free parent balance sheet and the value of underlying holdings support a much higher share value than the market recognizes. None of these proposals is an announced company action, but a combination of a tender, real-estate monetization and litigation CVR would create several discrete catalysts if the board engages.
9. INTERESTING SITUATIONS
Tripadvisor (TRIP US) — UPDATE (November 1 and 5). Tripadvisor completed the sale of its European restaurant platform TheFork to American Express for $700 million in cash, subject to closing adjustments, and then reported Q3 results on November 5. The remaining business is now a different mix of travel assets, with a substantial one-time cash realization that should prompt fresh scrutiny of the pro forma balance sheet and capital allocation. The transaction is closed; the investment question is what value remains and how much of the gross proceeds is truly available after taxes and other costs.
10. MISCELLANEOUS CORPORATE ACTIONS
Pantera Silver (PNTR CN) — UPDATE (November 3–4). The TSX Venture Exchange cleared Pantera’s resumption after the company filed overdue audited statements and the British Columbia securities regulator revoked its cease-trade order. CIRO confirmed trading would restart at 9:30 a.m. ET on November 5. The obvious opportunity, if any, is unusual price discovery after the suspension, but this is an illiquid exploration company with a recent compliance problem—not a valuation catalyst in its own right.
Upcoming catalysts
Appreciate you taking the time to read Weekly Snacks. I hope you have found at least some of these links/callouts to be interesting enough to dive into yourself.
If you haven’t already, consider hitting the subscribe button below and sharing this Substack with someone you know.
Until next week,
Paul Cerro
Weekly Snacks Twitter: @weeklysnacks
Personal Twitter: @paulcerro
Any feedback? Hit reply
Disclaimer:
Informational purposes only: This publication is provided by Weekly Snacks solely for informational and educational purposes. It is not investment advice, a recommendation to buy, sell or hold any security, or an offer or solicitation to transact in any security. It does not take into account any reader's investment objectives, financial circumstances or risk tolerance.
Independent due diligence: Each reader is responsible for conducting their own independent due diligence and evaluating the suitability and risks of any investment. This overview is a summary, not a substitute for reviewing the complete SEC filings, financial statements, risk factors and subsequent disclosures. Readers should not rely solely on this publication when making investment decisions.
Sources and limitations: Information is drawn from publicly available sources, including SEC filings, and may include company-reported figures, estimates and statements that have not been independently verified. Although care is taken in preparing this publication, its accuracy, completeness and timeliness are not guaranteed. Analysis reflects interpretations of the source materials as of the stated date and may be superseded by later filings or events.
Investment risk: Investing in securities involves risk, including the possible loss of principal. Historical financial performance, growth rates and operating metrics do not guarantee future results. IPO terms may change before pricing or completion, and an offering or exchange listing may not occur.