


Hello everyone,
It’s been a minute! Weekly Snacks was originally founded over three years ago as one of the first aggregators for investment pitches, general research, and interesting Tweets. To be frank, keeping up with it got tedious for me, especially while I was out building Cedar Grove Capital Management.
However, I still own Weekly Snacks, the domain, and its socials, and still wanted something to do with it that didn’t seem like a “job” to me.
In my own process for my fund, I do enjoy researching IPOs. I tend to find a lot of ‘short alpha’ there, which is why my performance with them has been so good (below).
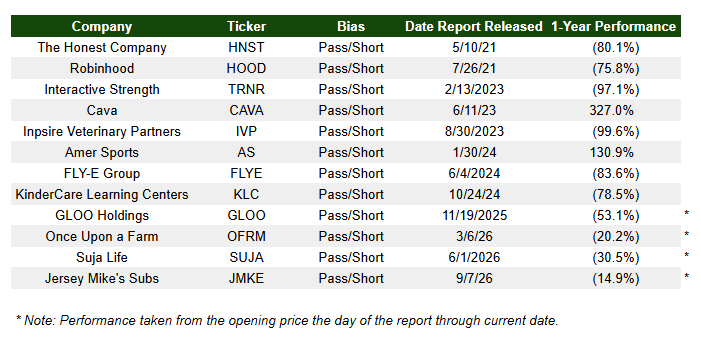
But the above are based on my full-blown notes on IPOs that I think are interesting enough to write about, not every IPO. I still sift through a lot of IPOs to see what might pique my interest and then decide if I want to write a full post on it afterwards. As I’m sure you know, there’s a lot of content out there to sift through, and there are only 24 hours in a day.
How can we decide what’s worth looking at?
Well, I have my own process, but when I got to thinking about it more, I felt that maybe it would be good enough to share via Weekly Snacks. This is why I’m relaunching Weekly Snacks as a quick IPO monitor that highlights a quick summary of the IPO (via AI), and if you want to dive deeper, you can download the AI-generated PDF. Sent out weekly, if there’s something to send out.
That’s it. Simple and to the point. It’s nothing that I don’t already do on my end for idea generation, and I’m just extending it to you all via this.
So please, take a look at our first iteration, and let me know your thoughts, comments, feedback, etc.
At the end of the post, you’ll find a quick survey (2 questions) on whether you like this or not. Your feedback would be greatly appreciated so I can make this better!
Also, this is completely free! Just enjoy it, and please make sure to like/subscribe if you think it’s helpful to your process.
This Week’s IPOs
Centinel Spine | Proposed NYSE: CNTL
Filing: S-1, October 7, 2026. Pricing: Not disclosed.
Centinel Spine sells prodisc artificial spinal discs, a motion-preserving alternative to fusion for eligible patients. Revenue increased 39% to $132.2 million in 2025 and 42% to $85.2 million in H1 2026. H1 gross margin was 82.2%, adjusted EBITDA was $15.5 million, and GAAP net income was $10.2 million.
The primary equity offering will fund debt repayment, offering costs, commercial expansion, R&D, instruments/inventory and working capital. Some repayments benefit related-party lenders. The initial S-1 does not disclose the price range, shares offered, proceeds or valuation.
Potential competitive advantages include an established clinical platform, regulatory approvals and expanding surgeon adoption. Disclosed risks include reimbursement, larger competitors, single-source suppliers and an Up-C structure with a tax receivable agreement allocating 85% of certain tax benefits to existing owners. H1 net income included a $3.8 million warrant/derivative gain, while 2025 free cash flow was negative.
What to monitor: Final pricing, the fully diluted economic share count, post-IPO debt, proceeds allocation, and the tax receivable agreement’s effect on future cash flows.
Source: SEC S-1

Georgia Banking Company | Proposed Nasdaq: GBC
Filing: S-1, October 2, 2026. Structure: Direct listing/resale, rather than a capital-raising IPO.
Georgia Banking Company, Inc. operates an Atlanta-focused bank serving commercial, real estate, private banking, mortgage warehouse and treasury clients. At June 2026, it had $3.26bn of assets, $2.84bn of deposits and 10 branches. Acquisitions of Georgia Primary in 2025 and Tandem in June 2026 expanded its franchise and affect financial comparisons.
The S-1 registers up to 7,040,514 existing shares. Selling shareholders receive sale proceeds; the company receives none and bears listing expenses. The opening public price is not disclosed. The filing’s $30 private-transaction price is historical context, not a public pricing estimate.
H1 2026 net interest income rose 19.3% to $55.9m and GAAP net income rose 97.5% to $13.3m. Net interest margin improved to 4.36%; adjusted net income, excluding after-tax merger expenses, was $15.9m. Improved earnings and a larger local network are business strengths. Credit and funding sensitivities include commercial real estate at 58.8% of investment loans, uninsured deposits at 44.1% and geographic concentration. The listing has no contractual shareholder lock-ups.
What to monitor: Opening-market price, organic growth versus acquired balances, deposit retention, credit quality and regulatory capital.
Source: SEC S-1.
TFP Group Limited | Proposed NYSE: TFP
Filing: F-1, September 25, 2026. Pricing: Not disclosed.
TFP Group Limited, known as The Fidelis Partnership, is a specialty insurance managing general agent. Fidelis Underwriting and Pine Walk originate risks on third-party insurance capacity; TFP earns placement and profit commissions rather than operating as an insurance carrier. Placement commissions represented 90% of H1 2026 revenue.
The proposed offering combines company-issued ordinary shares and selling-shareholder shares. Price range, share counts and net proceeds remain blank. Company proceeds and existing cash will repay part of the new term loan, with any remainder for general corporate purposes; secondary proceeds go to selling holders. The August refinancing established a $2.04bn term loan before IPO repayment.
H1 revenue increased 11.4% to $407.5m, while company-adjusted EBITDA rose 4.1% to $244.8m and its margin declined to 60.1%. GAAP net income was $127.5m, including $39.0m of equity-investment gains. Scale, specialized underwriting and long-term capacity relationships are strengths; 70% of LTM bound premium had long-term capacity support. Constraints include leverage, premium-cycle exposure and concentration: Pelagos supported 48% of LTM bound premium, net of reinsurance. A fiduciary-balance control weakness caused a balance-sheet restatement, without a stated earnings or cash-flow effect.
What to monitor: Offer valuation, debt repayment, ownership/float, commission margins, capacity mix and control remediation.
Source: SEC F-1.
TRex Bio | Nasdaq: TRXB
Filing: Final 424B4, October 9, 2026. Pricing: $14 per share, final prospectus.
TRex Bio, Inc. develops therapies that activate tissue regulatory T cells to address autoimmune and inflammatory disease. Its lead wholly owned candidate, TRB-061, is in a Phase 1a/b trial involving healthy volunteers and patients with moderate-to-severe atopic dermatitis. Phase 1b patient topline data are expected in mid-2027; TRB-071 is in IND-enabling development.
The final prospectus offers 8,333,334 primary shares at $14, producing approximately $116.7m gross and $103.5m estimated net proceeds. No secondary shares are included. Net proceeds plus existing liquidity fund approximately $90m for TRB-061, $10m for TRB-071 and remaining working capital/general purposes. Management projects funding into H2 2029 under its current operating plan.
H1 2026 revenue was zero, net loss was $29.3m and operating cash use was $27.0m. June cash and securities totaled $90.9m before the IPO. The tissue-Treg platform, defined pipeline and Lilly licensing relationship are strengths, but no approved products or product sales exist. Patient efficacy remains unproven; rising development costs, equity dilution and a technical-accounting control weakness are material risks.
What to monitor: TRB-061 patient data, TRB-071 clinical entry, spending against the stated plan and reporting-control remediation.
Source: SEC final prospectus.
Santa Ana Global Enterprises | Proposed NYSE American: STNF
Filing: F-1, September 18, 2026. Pricing: Indicative $13-15 per ADS; not final.
Santa Ana Global Enterprises, S.A. is a Spanish holding company pursuing planned-community projects in Chile, Colombia, Panama and Costa Rica. Its ordinary shares already trade on BME Growth as STNA. The proposed U.S. offering comprises 1,154,000 ADSs, each representing one ordinary share.
At the $14 midpoint, gross proceeds would be $16.16m and estimated net proceeds $13.53m. The latter includes deductions for already-paid and noncash costs and is not closing-date cash. Proceeds repay $1.5m of Yorkville principal plus an assumed premium; remaining funds support selected land/project payments, pre-development and working capital.
Latest audited FY2025 results show no revenue, a EUR3.02m net loss and EUR1.97m operating cash use. Year-end cash was EUR53,752. The 2024 inception-period profit largely reflected a noncash land-valuation gain, limiting comparability. A five-project, four-country pipeline and management’s development experience provide organizational strengths, but rights remain conditional and no pre-sales have commenced. Going-concern uncertainty, uncommitted construction financing and undocumented oral deferral of overdue Panama payments are significant risks. Company-estimated lifetime project investment is $1.075bn, far beyond proposed IPO funding.
What to monitor: Updated liquidity, definitive land/trust documents, payment arrangements, permits, binding financing, pre-sales and final dilution.
Source: SEC F-1.
Appreciate you taking the time to read Weekly Snacks. I hope you have found at least some of these links to be interesting enough to dive into yourself.
If you haven’t already, consider hitting the subscribe button below and sharing this Substack with someone you know.
Until next week,
Paul Cerro